

When I launched The Trajectory Africa podcast in 2021, one of my goals was to understand the ʼwhyʼ behind the capital flows—what made certain opportunities value-creating and VC-backable. It’s been an inductive process, in the sense that I derived “foundational” principles from the conversations that composed the first series of the podcast. These then informed the arcs of inquiry for the next two series on fintech and digital commerce and logistics. One of the reasons I started writing last year was to distill what I heard from founders, investors and thought leaders. To make the process more manageable, I decided to break it into three steps, and then write a three-part series to share the learnings from each step.
The first piece, What Iʼve Heard about Fintech, captures the “big picture” theory for why digitalizing African economies creates space to invest, the limits of that process, how fintech serves as foundational infrastructure, and five potential investment opportunities—trade-boosting credit, cross-border payments, (consumer) payments infrastructure, (niche) neobanking, and asset-based financing.
The purpose of the second piece, What Iʼve Learned about Fintech, is to capture a deeper understanding of these five opportunities, based on writing from, and conversations with, fintech experts.
The third and final installment is a vehicle to force myself to share an informed perspective on what I’ve heard and learned about fintech. In an ideal world, this would be a set of explanatory principles or a framework of some kind. What itʼs turned out to be, is a two-part reflection that marries theory and thought. Part 1 (this part), focuses on a high-level argument for the value of fintech. Part 2 will articulate and justify a series of conclusions Iʼve reached about the fintech opportunity (based on whatʼs come before).
Once I started writing What I Think, I realized how much the process would help me see and understand what I actually think. Further, organizing these thoughts on paper is likely to create the space to see and think a bit more. So, while Parts 1 and 2 are probably the last lengthy pieces Iʼll write about fintech, there could be a couple of others beyond this series if/as new insight starts to gel.
Why Fintech: The Short Version of a Long Story
As I mentioned, I derived principles for understanding the African tech opportunity as a whole from The Trajectory Africaʼs first series. Of the six original principles, Principle #2 served as the primary anchor because it asserts that: “The future of African venture opportunities is digitalizing African economies”. This suggests that technology is the key to reducing the cost of, and increasing access to, financial and health services, education, energy, food, and transportation. My conversation with Abraham Augustine, Ecosystem and Marketing Manager at Norrsken, explored the premise of digitalization and its limits. Essentially, the broader argument is roughly as follows.
The value to capture from investing in African tech startups is derived from digitalizing “informal” markets. How? Increasing the efficiency of supply chains boosts profitability and scalability. For example, when technology providers use AI to determine what goods to deliver where, by what route, the cost of logistics can drop significantly. Companies who adopt this technology like Diageo or KFC can improve their margins and perhaps grow their operations more efficiently. However, as Abraham pointed out, there are limits to digitalization. You can’t digitalize infrastructure that doesn’t exist and digitalizing what does exist doesn’t fully make up for the gaps. For example, an Uber app can’t coordinate drivers and passengers if there are no cars and bikes. But even if you use technology to help vehicles navigate, that doesnʼt fully eliminate challenges such as flooded roads (if there are roads at all). Unfortunately, these limits can potentially constrain the scale, profitability and growth of startups because standard VC growth logic assumes fully digital solutions with a low to zero marginal cost of producing and distributing more products. (Note: Standard VC logic refers to the current version, which supports primarily digital solutions. Previous versions have invested in physical products and asset-heavy opportunities.)
However, ‘Tayo Bamiduro, Co-Founder and CEO of MAX, explains how digital infrastructure can circumvent the limitations of physical infrastructure. MAX has built an asset-light platform for vehicle financing that allows it to connect asset financiers, asset owners, and drivers. More specifically, it gives credit providers access to embedded credit decisioning engines that enable financing to be provided. Still, leveraging 2G (physical) infrastructure to monitor vehicles is a critical element of their approach:
Being able to see where vehicles are 24/7, and in cases of exceptions, to remotely deactivate them — the underlying infrastructure needed to do this already exists. It’s just that no one had really brought all the pieces together, at least not until MAX did some of that work.
There is already roughly 99% coverage for 2G networks across the continent, which means wireless connectivity exists almost everywhere. By leveraging that telco infrastructure, you have line of sight to hardware wherever it is.
The telcos have built out massive infrastructure, but depending on who you ask, most are utilizing less than 5% of its potential and capabilities. They already make enormous amounts of money from data and voice, so they’re not always incentivized to build out other products that their infrastructure could support. For the most part, they rely on third parties, like MAX, to find compelling use cases for what they’ve built.
Hereʼs where fintech enters the chat. Building on digitalization as the crux of the opportunity, is Principle #4, which emerged from a pivotal conversation I had with Barbara Iyayi, CEO of Liquid Credit and Unicorn Growth Capital, on the role of fintech in Africa’s digital economies. It posits that: “Fintech is an important enabler for digitalizing African economies because it serves as foundational infrastructure.” As Barbara explained it, digitalizing transactions in the real economy, with an eye towards their core financing needs—payments, working capital, etc.—creates new business opportunities and revenue streams. Digitalizing traditional industries pulls them into the emerging digital economy, and spurs growth. From her point of view, fintech is the foundation of digitalization, and as such, the digital economy.
What this boils down to is an opportunity to provide Africans with better ways to move money and transact. Of course, there are different points of view on how to achieve this. Toffene Kama, Principal Investor at Mercy Corps Ventures, shared his thinking some time ago on velocity as a possible pathway, at least conceptually. But I’m revisiting the core argument here to emphasize the need for, and utility of, digitally-enabled financial infrastructure.
What Toffene suggests is that from a macroeconomic perspective, a high velocity of money can actually be fostered by digitizing cash, which can greatly reduce the friction that slows down money movement. When money moves faster, it can be directed to productive uses more rapidly. For example, during a podcast prep call with Lori CEO and Co-Founder, Jean-Claude Homawoo, he helped distill the “financial story of logistics” as the narrative arc for his episode. Truckers borrow to bridge the gap between service delivery and payment. Why? Because truckers pay the cost of moving cargo, and it takes 30-90+ days to be paid for doing so. These payment terms constrains truckersʼ profitability and growth, and hampers the flow of funds and goods through supply chains. And ultimately, it shifts the unwieldy responsibility for providing working capital onto startups like Lori, many of which lack the balance sheets and financial expertise to manage it safely.
Arguably, this is a velocity problem, caused by an infrastructure deficit. African supply chains are long and complex, which adds time and cost to transporting goods. Both are presumably borne by middle men who lengthen the chain, and increase the cost of transporting goods. But they also bear the burden of longer chains and higher costs, in the form of payment terms that require them to prepay for the expenses of moving cargo, and then wait months to be compensated.
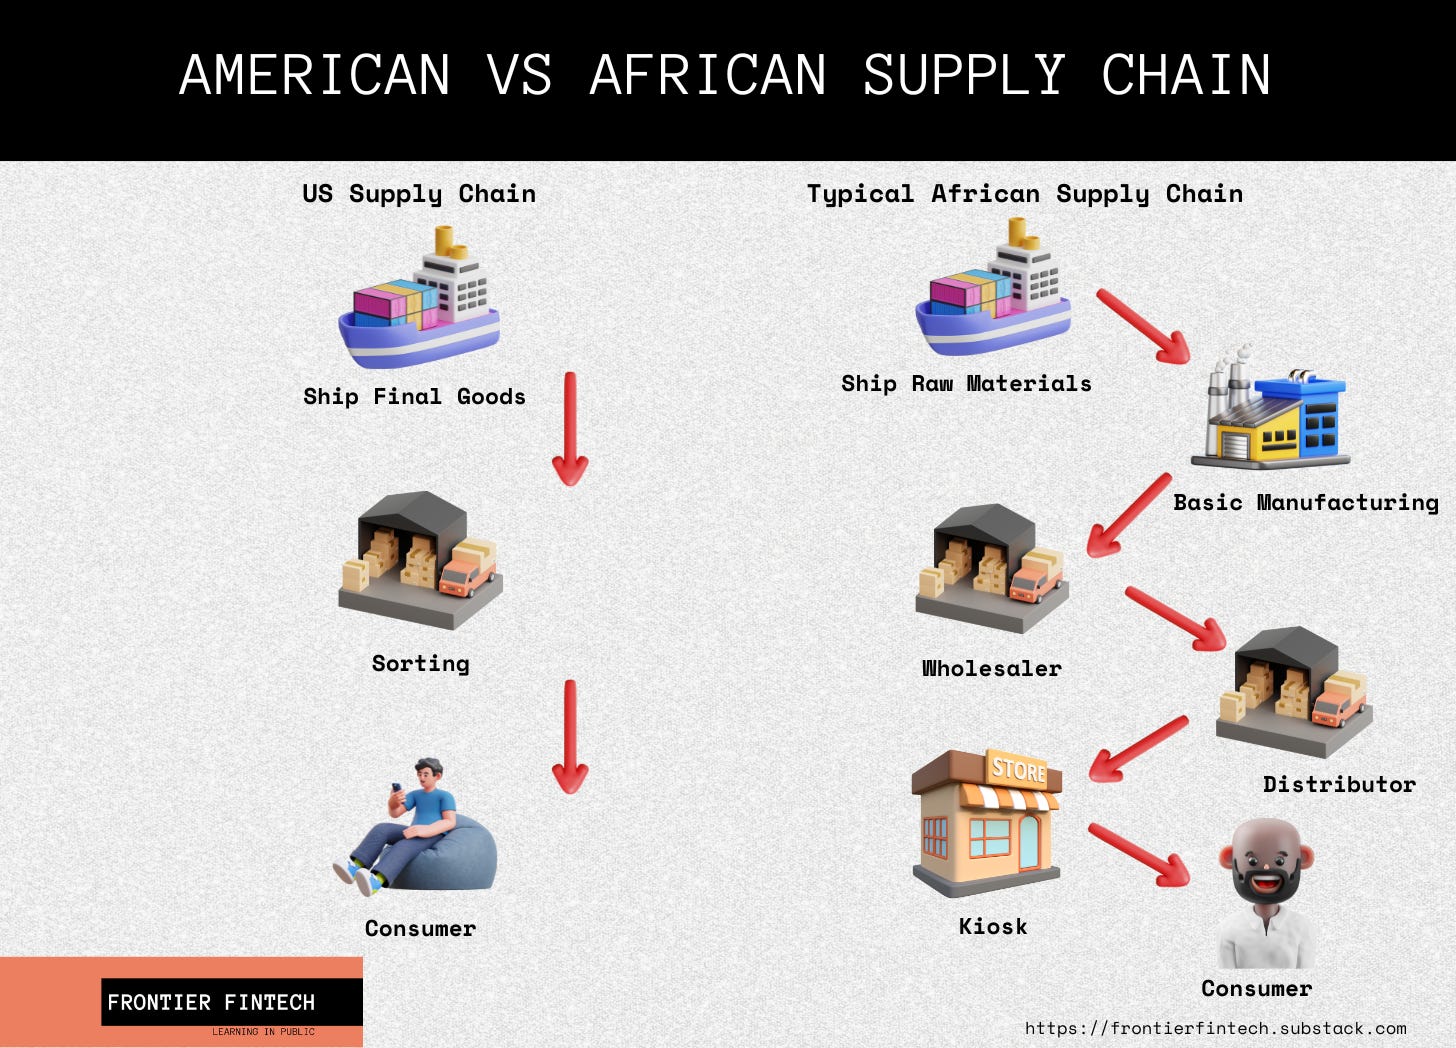
Short of altering the structure of these supply chains (which B2B e-commerce startups have struggled to use technology to do), enabling instant, digital payments keeps money moving within the financial system. For example, as Toffene points out, merchants typically collect VAT, which governments have to recover from them later. This leads to evasion, delays, and eventually, penalties. With digital payments, VAT can be paid to the government instantly and directly. As a result, they can fund and launch meaningful projects such as road construction sooner. In Senegal, mobile money operators collect more than $250M monthly in VAT. To do so more efficiently, the government could explore “just-in-time”VAT. Every time a customer pays a merchant from a digital wallet, VAT could be deducted automatically.
In short, Toffene is arguing that credit has been used to fix problems caused by money that is stuck or slow-moving due to sub-optimal norms (truck drivers pre-paying cargo shipment expenses), processes (payment terms), and infrastructure (complex supply chains). Credit used to manage systemic friction doesn’t necessarily result in increased growth and productivity. It could just be a way to keep businesses operating.
But if payments across the financial system settled faster, perhaps this would alleviate the need for survival credit. This suggests that infrastructure such as stablecoins and instant payment systems, which “unstick” money, can also direct it toward productive uses (and potentially recycle it) faster. We already see this in how mobile money operates. Agents deposit cash at a bank or with an aggregator in exchange for float, or electronic value. When a customer cashes in, they hand the agent cash and receive float. When a customer cashes out, they send float to the agent and receive cash in return. So, the faster that cycle runs, the more transactions the same pool of capital can fund.
Toffene also notes that Starbucks holds nearly two billion dollars in prepaid customer balances, which amounts to working capital the company didn’t technically borrow. This is bank-like behavior, an idea we’ll return to in Part II. Just to be clear, thinking about velocity isnʼt an attempt to discredit credit as a tool. It does call into question, however, when and under what circumstances credit is put to productive use.
Digitally-Enabled Financial Systems and the Fintech Landscape
So, how does this “macro” level framing translate into tangible opportunities? For the remainder of this piece, I’ll narrow the funnel to describe what a digitally-enabled financial system delivers, which should help define the boundaries of opportunity. Then, we’ll switch to a market-level perspective to look at characteristics that both shape and constrain that opportunity. In the next piece (Part 2), Iʼll share observations about how fintech landscape seems to be evolving.
What Should a Digitally-Enabled Financial System Deliver?
In his piece First we must build Infrastructure, Samora Kariuki laid out the key aims and components of a functional, digitally-enabled financial system. This creates a framework into which the five opportunities I described in my previous pieces—trade-boosting credit, cross-border payments, (consumer) payments infrastructure, (niche) neobanking, and asset-based financing—can be placed. Whatʼs below remixes Samoraʼs thinking somewhat in response to my own learning, but still highlights what a digitally-enabled financial system in Africa does:
Drive financial inclusion. Financial inclusion could be considered its own space, emerging within and alongside microfinance. From a technology perspective, there was a heavy initial focus on onboarding people into financial systems via digital wallets. In the last few years, however, the emphasis seems to have shifted from financial inclusion to financial health—the concrete ways in which financial services improve people’s lives and prospects. The Gates Foundationʼs decision to wind down its financial inclusion work might be emblematic of that transition.
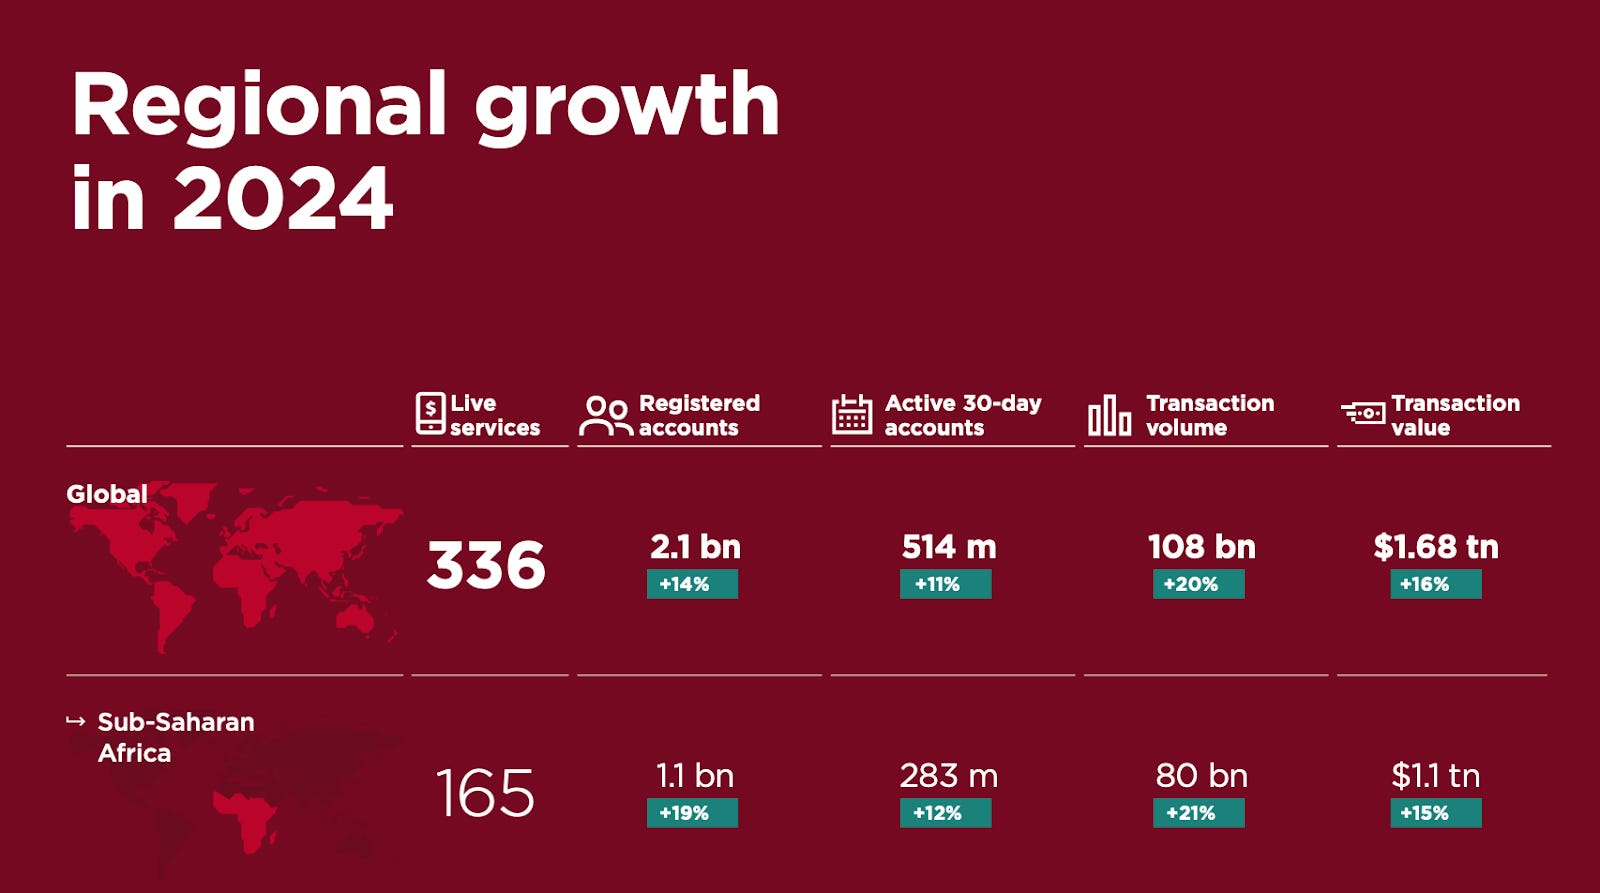
In the context of African fintech, questions have been raised about the extent to which fintech products boost inclusion. Of course, one can point to the spread of digital wallets and mobile money as indicators. But when one considers the barriers to adoption highlighted earlier, the proportion of wallets in use, and how much money is stored and saved in them, the depth of inclusion comes into question. According to the GSMAʼs report, there were 1.1B registered accounts in Africa in 2024, of which 283M were active within 30 days.
Source: GSMA
However, the World Bankʼs Global Findex from 2021 indicates that in Kenya, 59% of adults used their accounts to store money, compared to 45% who used it to save. Across Sub-Saharan Africa, 39% of mobile money account holders used their wallets to save. Strikingly, the most common barrier to getting a mobile money account was lack of money. Clearly, having a wallet means very little if you have no money to put in it.
Still, one can argue that fintech is fundamentally about inclusion because of the sheer number of unserved and underserved Africans. Historically, the cost to serve many African customers has been too high and the revenue too low for financial institutions to deploy traditional infrastructure such as bank branches. But digital solutions were meant to be the great equalizer. Tosin Eniolorunda, CEO of Moniepoint, actually links inclusion to Moniepointʼs mission: “....We founded the Company out of a genuine passion to widen financial inclusion and to help African entrepreneurs realise their potential. That same passion drives the work we do today…”
As Moniepointʼs strategy illustrates, it’s the building of “phygital” infrastructure—agents for acquisition and distribution and AI and blockchain technology for operational efficiency—thatʼs carving a new path forward. In Part II, I’ll explore how technology increases efficiency (through automation and bypassing traditional systems) and reduces the cost to serve less profitable customers. For now, a good starting point is a broad rationale for technology-enabled financial systems that Samora shares in the second episode of The Trajectory Africa’s fintech series:…if you were to build a financial system now, why wouldn’t you leverage the most advanced technologies? Technology enables you to leapfrog, [and] look at things in terms of first principles better. An example is Kenya is rolling out a new ID system. You have to say, what can you actually accomplish with technology, with an ID system? You need to enable this ID system to be searchable. You need a database that can be queried across multiple service providers. You’ll eventually land on the conclusion that [you] need to use the latest technology. If you’re to build a payment system, would you build one where people need to present a physical paper in a physical location? No, you can do something better than that.
To take a more granular perspective, Accion Ventures describes how automation creates opportunities for short, medium, and long term impact. In the short term, more customers are served due to lower costs and increased operational efficiency. For example, API-based automation in financial infrastructure
significantly reduces costs and makes processing much faster. According to Accion, “For financial institutions operating in emerging markets, financial infrastructure addresses fundamental pain points: high onboarding costs, limited customer data, manual reconciliation, and fragmented banking relationships. Take just one example: API-based automation platforms have been shown to reduce costs by up to 80 percent and accelerate customer processing time from days to minutes. This cost and time compression is what makes it viable for lenders and platforms to serve low-income or small-ticket customers.”
In the medium term, customers use financial products more, which improves financial health through better delivery. Finally, in the long-term, inclusion becomes more of a systems-wide state.From this perspective, all five opportunities contribute to inclusion, broadly defined. However, neobanking is the most direct expression of an effort to serve customers that are unwanted by traditional banks because they are unprofitable to serve. As I’ll cover in Part II, African fintech products and services are evolving beyond the “basic infrastructure” phase associated with inclusion, into more “advanced” propositions.
Enable credit to get to whoever deserves it. Qualifying who “deserves” credit is above my pay grade. However, the two credit-related opportunities I’ve identified—trade-boosting credit and asset-based financing—are lending opportunities that improve productivity for companies and consumers. This implies that credit should go to people and institutions who are producing goods and services for trade. More specifically, lending for trade is needed because Africa’s long, complex supply chains can result in payment delays. Fortunately, there are potential solutions to this problem. I wrote about these in detail here, but letʼs recap briefly. (You can also read directly from the source, here.)
Trade-boosting credit
Pre-shipment finance could represent a large opportunity because there are few players providing it, and it applies to both domestic and cross-border trade:Supply chain finance allows suppliers to receive financing (often through credit from buyers) before goods are produced, enabling them to be manufactured, stored, and shipped. This applies to both domestic and international supply chains. More specifically, pre-shipment import finance allows suppliers to obtain credit that’s secured by orders from large companies.
Trade finance provides credit to SMEs that are trading across borders. Here, as with supply chain finance, there’s an opportunity to provide capital to support suppliers before goods are produced, distributed, and shipped. Pre-shipment export finance provides suppliers with capital for inputs, production, and shipping before the buyer commits to a sale, and requires deep knowledge of the goods and the industry, as well as the ability to temporarily own and track the assets.
Post-shipment (supply chain or trade) invoice financing is more compelling from a risk-management perspective, especially in emerging markets where KYC, verification, and trust may not be as well established, and the systems are not as well structured, as Lina Kacyem explained.
Asset-based financing
Productive asset-based financing, demonstrated by the success that companies like m-Kopa and Watu have had in financing mobile phone purchases, is another opportunity. These sorts of models help “informal” economy workers to obtain productive assets such as phones, motorbikes, or cars, because banks won’t serve them due to their lack of credit history. These assets allow them to create or increase incomes, or spend less money on critical goods and services. Where feasible, technology can track and deactivate an asset if the borrower defaults, turning it into collateral. If a loan is repaid successfully, the track record of payments creates a digital credit history that can qualify borrowers for other financial products such as insurance.
Collateral-free lending, potentially unlocked by unifying multiple sources of financial data to create a complete picture of what a business earns, is another opportunity.
My sense is that some types of credit deployed to facilitate trade can be complementary to the notion of friction-free, velocity-boosting digital cash flow. If the credit is extended on the basis of access to digital transaction data (which is what Sote tried to deliver), and the funds are delivered digitally, the potential for productive credit is high.Empower Africans to move money freely. This is shorthand for three related principles I’ve combined into one: 1) enable Africans to transact anywhere;
2) enable easy intercontinental money movement; and 3) drive trade and commerce via easy payments. The overarching logic is that trade contributes to economic development, and the frictionless movement of money supports trade. Not surprisingly, two of the fintech opportunities I identified: (consumer) payments infrastructure and (stablecoin-powered) cross-border payments fit within this category. Arguably, the latter is a subset of the former. The payments infrastructure category acknowledges that payment service providers (PSPs) like Paystack create value by using APIs to make it easy for businesses to accept many forms of payment from consumers. Network aggregators like Onafriq also create value by connecting payment rails across platforms like mobile money. Similarly, once those payments cross borders, stablecoins make the money move faster, and more cheaply.Enable transactional identities so as to allow customization and personalization. This job-to-be-done doesn’t map neatly to any of the five opportunities, but it does point to an expectation for AI to process data that can unlock insights that lead to customized offerings, such as borrower-specific loan amounts and rates.
Letʼs wrap up with a few of the fintech market characteristics described in McKinsey’s 2021 report, The end of the beginning: Unlocking the value of African fintech. They’re still relevant today, and help set the stage for Part II—a discussion of how fintech opportunities are evolving:
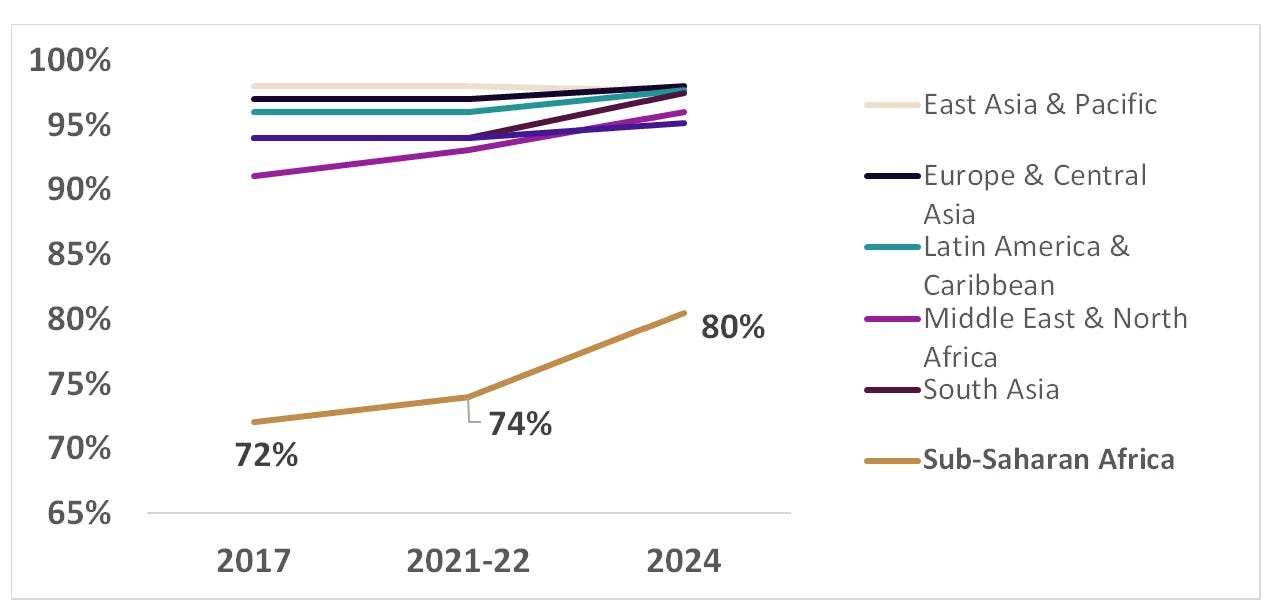
The absence of critical infrastructure “shrunk the addressable market” and hampered the spread of fintech services. The report cites gaps in internet and identification coverage. For example, in 2020, internet penetration was below 50% in five countries—Cameroon, Côte d’Ivoire, Nigeria, Tanzania, and Uganda. This was still true in 2024 according to DataReportal. Additionally, more than 40% of the population lacked formal identification. In 2025, the World Bank’s ID4D-Findex data indicated that adult ID coverage in Sub-Saharan Africa was about 80%, up from 72% in 2017. But that doesnʼt reflect the degree to which digital identification such as Nigeriaʼs bank verification number (BVN) is available as an enabler of digital transactions.
Reaching profitability in Africa is more difficult than in other regions. In fact, itʼs almost four times harder than in Latin America and thirteen times harder than in the EU. The reasons for this are covered by the next three points.
African consumers earn the lowest income (of anywhere in the world). For Africans, personal consumption expenditure (PCE) is as much as ten times lower than in North America ($1,505 per capita versus $49,423) and five times lower than in Europe. Of course, limited consumption power constrains the amount of revenue a fintech can earn from a customer.
Many fintechs have to spend much more to acquire customers than they can earn from them. For example, some companies have customer acquisition costs (CAC) of $20 per customer as compared to only $7 in revenue. Unfortunately, customer retention (LTV) is also a challenge. Even if a fintech attracts customers via competitive pricing, that customer will probably depart if there are better deals available. This makes it hard to generate recurring revenue.
B2B companies have stronger unit economics than B2C companies. In fact, on a per customer basis, African companies generate comparable amounts of revenue to global companies, and up to twice what they spend per customer. Perhaps this partially explains why infrastructure players that started as B2B providers, such as Flutterwave and Interswitch, achieved market leadership.
And that brings us to the conclusion of What I Think about Fintech: Part I. All the “big picture” framing—why digitalizing African economies is an opportunity, the role of fintech rails in efficient transactions, what a digitally-enabled financial system delivers, and what characteristics define fintech markets—is done. Next stop: What I Think about Fintech: Part II.